The Auctions Saved the Breakout — Now Core CPI Has to Confirm It (12–16 Oct 2026)
Hello out there,
Here's the roadmap for the week. Last Sunday I said 5.34% on the 10-year decided whether NQ's record was a breakout or a top. Yields crossed it, and then the bond market blinked first. This week September CPI gets the deciding vote, so I'll go top-down, then lay out the NQ, BTC and gold maps and what flips each bias.
The risk meter has moved from Mixed to Neutral. That's a stand-off, not a contradiction. Equities finished green and USD/JPY pushed higher, both risk-on, but gold caught a bid, the dollar index added 0.3% to 102.21, Brent is back above $104 and the 10-year still yields 5.24%. VIX closed Friday at 14.84: Normal, but barely above Compressed, so options are hardly paying for Wednesday's CPI risk. That's room for standard size, not a reason to stretch it. NQ is still trending up, gold has turned into a range, and bitcoin has slipped into a down-trend.
Regime read — Risk: Neutral. Vol: Normal. NQ: Up-trend. BTC: Down-trend. Gold: Range.
Where the week closed
| Market | Friday close | Week | Context |
|---|---|---|---|
| NQ (Dec futures) | 31,108.75 | +0.2% | Cash Nasdaq-100 30,883; record 31,616.50 Tue |
| Gold (Dec futures) | $4,216.30 | +1.3% | Spot $4,194; week low $4,091 futures, $4,066 spot |
| Bitcoin | ~$83,000 (Sun) | −4.0% | 200-day EMA ~$75,800; 50-day ~$80,000–$80,800 |
| US 10-year | 5.24% | −4 bp | Wednesday intraday high ~5.36%, highest since 2002 |
| Dollar index | 102.21 | +0.3% | Firmer dollar and firmer gold |
| USD/JPY | 158.34 | +0.3% | 160 is the intervention zone |
| Brent (Dec) | $104.72 | +2.4% | Hormuz still shut; Isaias shut-ins |
| VIX | 14.84 | −3.1% | Normal, one tick off Compressed |
NQ and gold levels in this post are December futures unless noted.
Start with the line. The 10-year ran to roughly 5.36% intraday on Wednesday, its highest yield since 2002, into a $39 billion auction. NQ dropped 1.38% Thursday, partly on rates and partly on a report that OpenAI's annualized revenue run rate was about $50 billion, not the roughly $70 billion that had been circulating. Then the auctions did their job. Indirect bidders, the bucket that includes foreign central banks, took 80.3% of the 10-year against a 72.4% average over the prior ten. The 30-year went well too, and the 10-year finished at 5.24%. There is a buyer above 5.30%. For now.
A correction first: last week I wrote that the Fed held in September. It didn't. It hiked 25 basis points to 3.75–4.00%, and the minutes show all 19 participants backed the move, with most saying another hike "would likely be appropriate by year end." Governor Waller said Thursday that more hikes are likely needed. Futures price roughly a 20–25% chance of a hike at the October 27–28 meeting. CPI moves that number.
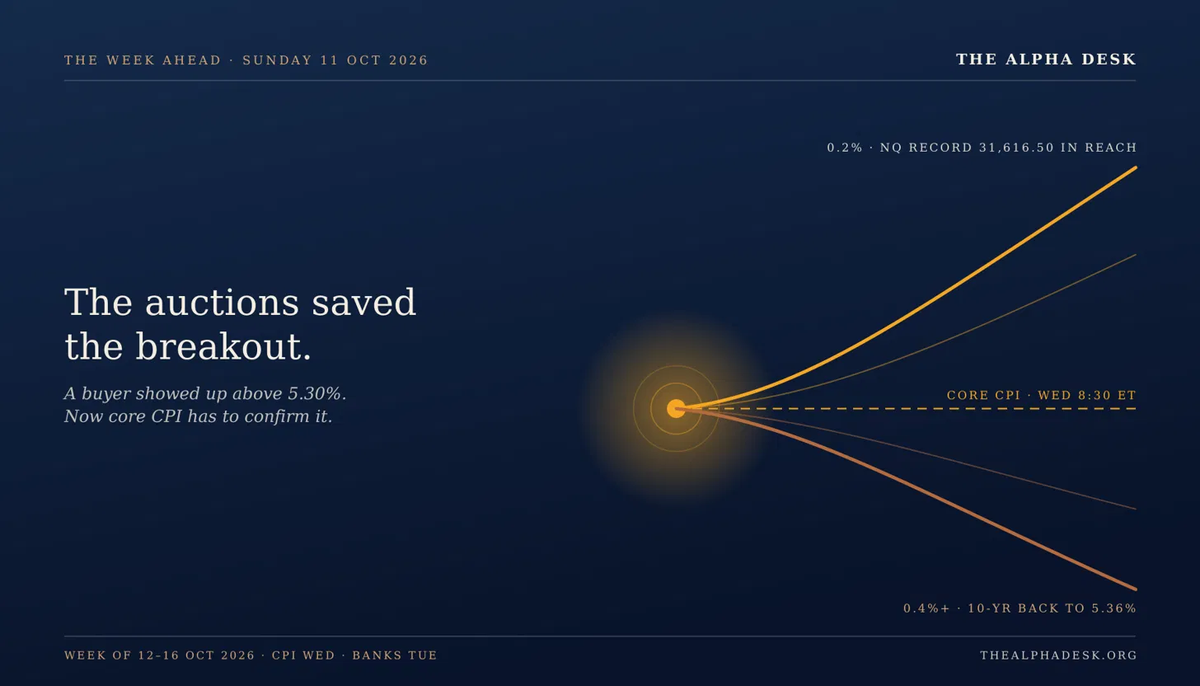
September CPI lands Wednesday at 8:30 a.m. ET. Consensus is +0.6% m/m and 3.6% y/y for headline (from 3.4%), but only +0.2% and 2.5% for core. That gap is energy. If headline runs hot and core lands on consensus, the Fed has an oil problem, not a demand problem, and markets can live with that. If core prints 0.4% or higher, October becomes a live meeting, the 10-year goes back after 5.36%, and NQ takes the hit. Therefore I'm watching core m/m, not the headline. Thursday's PPI and retail sales (consensus +0.3% after +1.2%) finish the story.
Energy is still the fuse. December Brent settled at $104.72, up 2.4% on the week. Trump said Washington is having "productive discussions" with Iran and ruled out a strike before the November 3 midterms; Tehran is reviewing a US response on reopening the Strait of Hormuz. Constructive, but the strait is still shut. Hurricane Isaias also shut in close to two-thirds of Gulf of Mexico output, so restart pace matters for crude. USD/JPY closed at 158.34, under two big figures from the 160 zone where Tokyo has stepped in before. A hot CPI pushes it there, and intervention becomes a tape-bomb for the yen carry trade, where you borrow cheap yen to fund higher-yielding positions. Monday is Columbus Day: stocks trade, cash bonds don't, so the first clean yield read is Tuesday.
NASDAQ (NQ)
December NQ closed Friday at 31,108.75 (cash Nasdaq-100: 30,883), up 47 points on the week, but the range tells the story: a record at 31,616.50 Tuesday, a flush to 30,792 Thursday, a rebound Friday. Last week's first support was 30,750, and Thursday's low held 42 points above it. Higher high, higher low. The up-trend tag stays.
My level map: 30,950 is first support, where Monday's and Friday's lows sit within five points of each other. Below that, 30,792 has to hold; lose it on a close and 30,350 is back in play. Overhead, 31,466 (Thursday's high, where the selling started), then the record at 31,616.50.
I'm constructive, but not adding before CPI. Earnings season starts too: banks Tuesday, ASML Wednesday, TSMC Thursday. TSMC already pre-announced Q3 revenue above consensus, so Thursday is about guidance, and after the OpenAI headline it's the cleanest read on AI capex demand. A hot core print with the 10-year back above 5.30% flips me neutral. A close below 30,792 flips me flat.
BTC
Bitcoin gave the signal I said to respect, then didn't follow through. It closed Thursday near $81,730, below the $82,000 floor I flagged last week, after tagging roughly $80,400. That close was supposed to point toward the 200-day EMA, now near $75,800 (the simple 200-day is lower, near $72,000). Instead buyers reclaimed $82,000 Friday, and it sits near $83,000 this weekend. But daily highs stepped lower Monday through Thursday, from $86,995 to $83,509, so I'm tagging it down-trend, not range.
Flows explain it. US spot ETFs bled $681.1 million in the week to October 9, their worst week since late June. The line is the $80,300–$80,400 low; the 50-day average sits right there too. Lose it and $75,800 is next. Resistance is $84,000, then $86,000–$87,200. I don't want to be long under $84,000 into CPI. A reclaim and hold above it is what turns Thursday's breakdown into a shakeout.
Gold
Gold went from bleeding to basing. December futures closed at $4,216.30 (spot $4,194), up 1.3% on the week, after a Wednesday wick to $4,091.20 through the $4,100 support I flagged last week. It got bought within a day, and the driver was the one I said I needed: a lower 10-year. Note that it rallied with the dollar index up 0.3%, so this bid is about yields, not the dollar. Friday's high of $4,233.70 ran straight into the $4,200–$4,230 resistance band, and it closed just under it.
So this is a range, roughly $4,090 to $4,235, not a new up-trend, and still about 25% below January's record near $5,585. A daily close above $4,235 opens the $4,300 shelf. A hot CPI that drags the 10-year back toward 5.36% puts $4,090 back in play. I'd rather buy a hold of $4,140–$4,157 (Wednesday's and Thursday's closes) than chase a breakout into CPI.
The week that matters
- Mon 12 Oct: Columbus Day. Stocks open, bond market closed; Cleveland Fed's Hammack speaks
- Tue 13 Oct: JPMorgan, Goldman Sachs, Citi and Wells Fargo earnings; Fed's Waller, Barkin and Collins speak
- Wed 14 Oct: US CPI (Sep), 8:30 a.m. ET; Beige Book, 2:00 p.m. ET; Bank of America, Morgan Stanley and ASML earnings
- Thu 15 Oct: US PPI and retail sales (Sep), jobless claims, Philly Fed; TSMC earnings
- Fri 16 Oct: Industrial production (Sep); monthly options expiration
- Tue 27–Wed 28 Oct: FOMC. CPI decides whether it's live
The playbook this week is patience until Wednesday at 8:30. A buyer above 5.30% bought equities a reprieve, not a green light. With vol normal, I'm comfortable carrying standard size on NQ longs defined against 30,792, but I'm not adding until core CPI is out. Bitcoin gets no longs under $84,000. Gold gets bought on holds, not chased. Core at 0.2% keeps the breakout alive; 0.4% or higher puts 5.36% back on the screen.
Disclaimer: This post is for education and discussion only and does not constitute investment, legal, tax, or accounting advice. Markets are risky; you can lose more than you invest. Do your own research and consider your objectives, experience, and risk tolerance before acting. Past performance is not indicative of future results.